Military Relocation and VA Loans: A Straight Guide for Sarasota-Bound Veterans
How the VA loan actually works, what a PCS timeline looks like on the ground, and the Florida costs that catch people out — for anyone moving to Sarasota, Bradenton, or Lakewood Ranch.
By Akeme Foster · September 16, 2026 · 5 min read
A move on orders is not a normal move. You often learn where you are going a few weeks before you have to be there, you may be doing the whole search from another state or another country, and the paperwork does not wait for you to settle in. If Sarasota, Bradenton, or Lakewood Ranch is your next stop, here is a plain walk-through of how the VA loan side works and how the local search usually goes. I keep a fuller guide at military relocation if you want the longer version.
Why so many service members land in Sarasota
Sarasota was ranked #1 in both "Best Cities After Service" and "Best Cities for Retired Veterans" in Navy Federal Credit Union's 2024 Best Cities After Service report, produced with Sperling's BestPlaces. Worth being precise about what that measures: livability and appeal for retirement after service, not how easy it is to buy a house here. Still, it explains why so many of the calls I get start with "a buddy of mine moved to Sarasota."
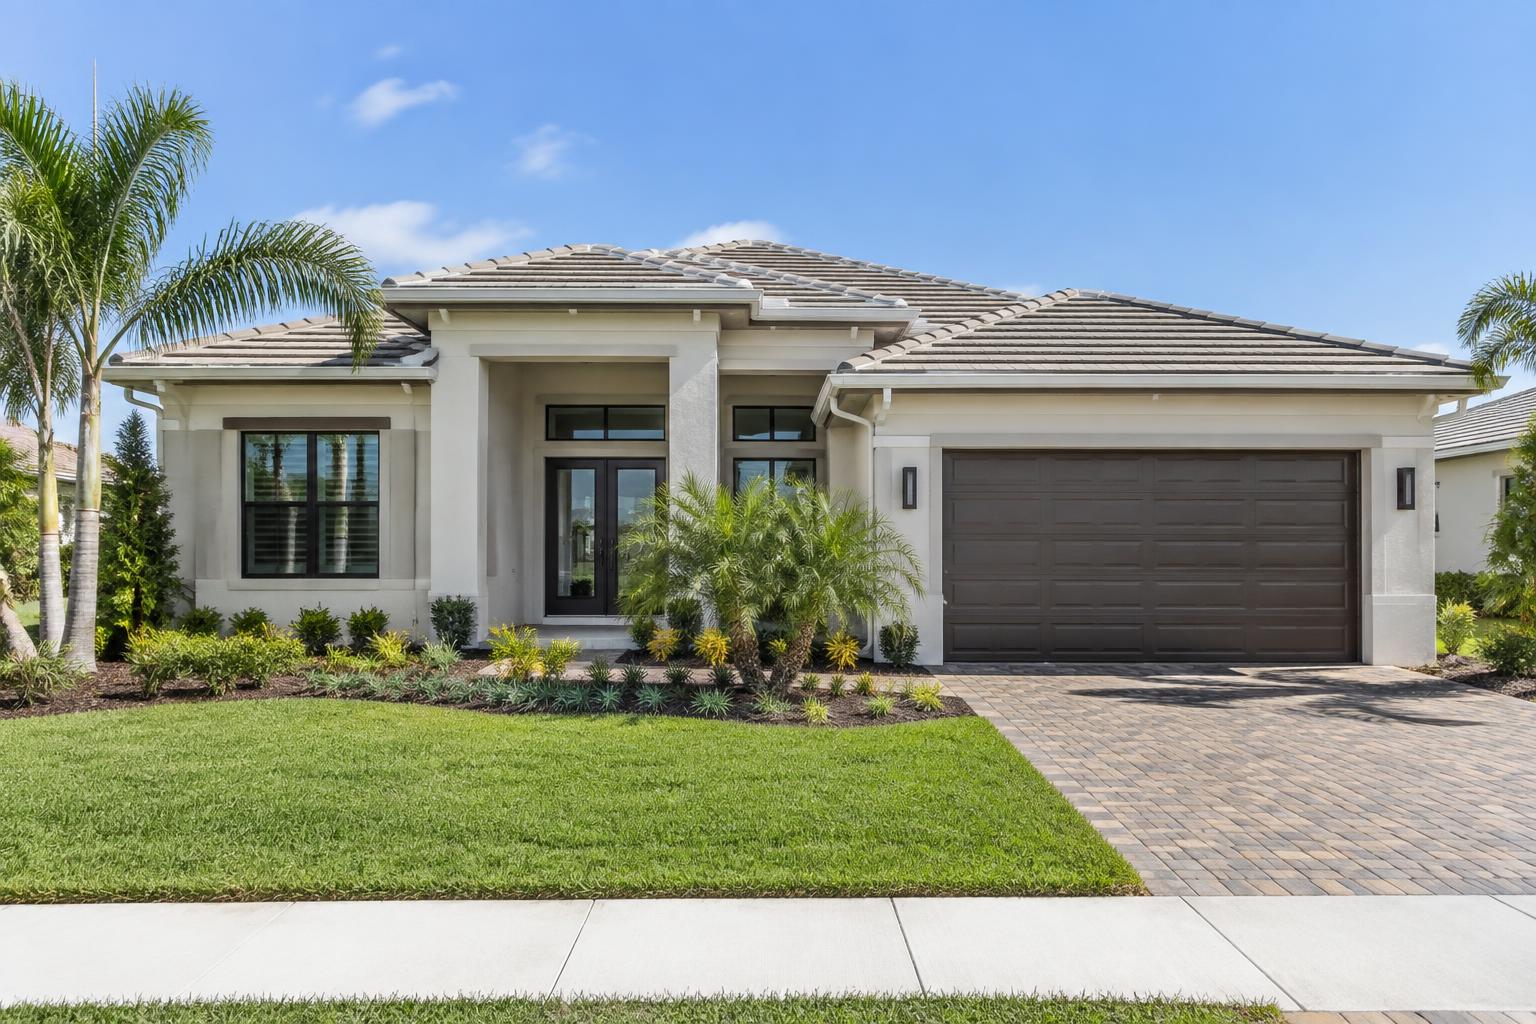
Practically, the area gives you a spread of options. Lakewood Ranch is heavy on newer construction and master-planned neighborhoods. Bradenton runs older and generally less expensive. Sarasota proper covers everything from small mid-century homes to waterfront. Which one fits usually comes down to commute, schools, and how much yard work you want to own.
The VA loan, in plain terms
The VA does not lend you the money. It guarantees part of a loan made by a regular lender, and that guarantee is why the terms are what they are.
- Who can use it: generally veterans, active-duty service members, National Guard and Reserve members who meet service requirements, and some surviving spouses. Eligibility is established with a Certificate of Eligibility.
- No down payment is required on most purchases within your entitlement.
- No private mortgage insurance, which is the piece that quietly adds to a monthly payment on other low-down-payment loans.
- A VA appraisal and minimum property requirements apply, so the home itself has to hold up.
- The benefit is reusable — it is not a one-time thing.
I am not a lender, so I will not put numbers on this page. Current limits, rates, funding fee amounts, and what you personally qualify for come from a VA-approved lender looking at your file. Treat everything here as general information, not financial advice. Getting that conversation done early is the single biggest favor you can do yourself, because a full pre-approval is what makes your offer credible when you are competing from three time zones away.
What sellers here actually think about VA offers
There is an old rumor that VA offers are harder to close. In practice, what a listing agent reacts to is preparation: a full pre-approval, a realistic timeline, and an agent who answers the phone. When those three are in place, a VA offer reads like any other strong offer.
Buy now or rent first
Both are defensible. Renting first buys you time to learn the area and avoids committing during a chaotic month. Buying immediately starts building equity and locks your housing situation down before the reporting date. What tips the decision is usually how firm the assignment is and how much of the area you already know.
If you rent first, ask about a military clause in the lease — language that addresses early termination on qualifying orders. Federal protections for service members exist as well. I am not an attorney, so have anything you sign reviewed by legal assistance on your installation before you rely on it.
A timeline that usually works
- As soon as orders look likely: talk to a VA-approved lender, start the Certificate of Eligibility, and set a rough budget.
- Eight to ten weeks out: narrow to two or three areas. This is where video walkthroughs do the heavy lifting — I can walk a house on a call and show you the parts photos never show.
- Six weeks out: write offers with an inspection period you can actually use, even remotely.
- Under contract: inspection, VA appraisal, insurance quotes. In Florida, insurance and flood coverage move the monthly payment more than people expect, so price them early rather than at the end.
- Closing: remote and mail-away closings are routine here if you cannot be in the room.
The Florida-specific things nobody warns you about
Homeowners insurance, flood zone, roof age, and HOA or CDD fees can change your all-in monthly cost more than the list price does. Two homes at the same price can be hundreds of dollars a month apart once those are added in. Ask about all four on every home you take seriously.
How I help
I served in the Army and later worked with the Department of Defense before moving into Florida real estate, so a PCS window is not an abstraction to me. That mostly shows up as video tours instead of "come see it Saturday," scheduling that bends around your report date, and straight answers when a house is not worth your one trip out here.
If a move is on the table, tell me where you are coming from and roughly when you have to be here. That is enough to start. The full guide, including a current Sarasota market snapshot, lives on the military relocation page.
Step-by-step answers on VA loan paperwork, down payment and closing cost help, and how the timing usually falls are in the relocation FAQ.- military relocation
- VA loans
- Sarasota
- veterans
- PCS